
The Huntington River flooded the valley towns of central Vermont in July 2023. A year later, in July 2024, it flooded them again. Huntington, Starksboro, the smaller settlements along the tributaries of the Winooski — people were still patching drywall from the first flood when the second one came through and pulled it back off the studs.
After the water went down the second time, the federal government offered buyouts. Some households took them. Some didn't. The ones who didn't all show up in municipal records and planning documents under a single heading: remaining residents. Tidy phrase. What it hides is that the people inside it may share nothing but a mailing address and a river that won't leave them alone.
What mitigation bought
Amy Seoane and Justin Houghton lived on Huntington Acres, a short road along the river. They'd been flooded before — the property took water in 2019, and they responded the way the guidance says to respond. Trucked in fill to protect the lot. Elevated the garage where Houghton, an airplane mechanic, kept his equipment.
Five feet of water crossed their backyard in July 2024. Flooded the bottom floor. Thousands in damage. Seoane told VTDigger that going further would cost real money, might not work, and didn't look sustainable unless something changed across the whole watershed. She applied for a FEMA buyout and said they might leave with or without one.
So here's a household that did the recommended things, paid for them, and then watched the river come through anyway at a depth the recommendations weren't sized for. Worth holding onto when you consider the people still living in that valley, on that floodplain, watching that same water. Not all of them have reached a conclusion about the river. Some of them are there because the arithmetic of leaving doesn't come out.
What the walkway costs
A few miles south, in Starksboro, Mellissa O'Bryan's driveway bridge — the short span between her house and Ireland Road — went out in the same flooding. Her car went with it, along with a piece of the road.
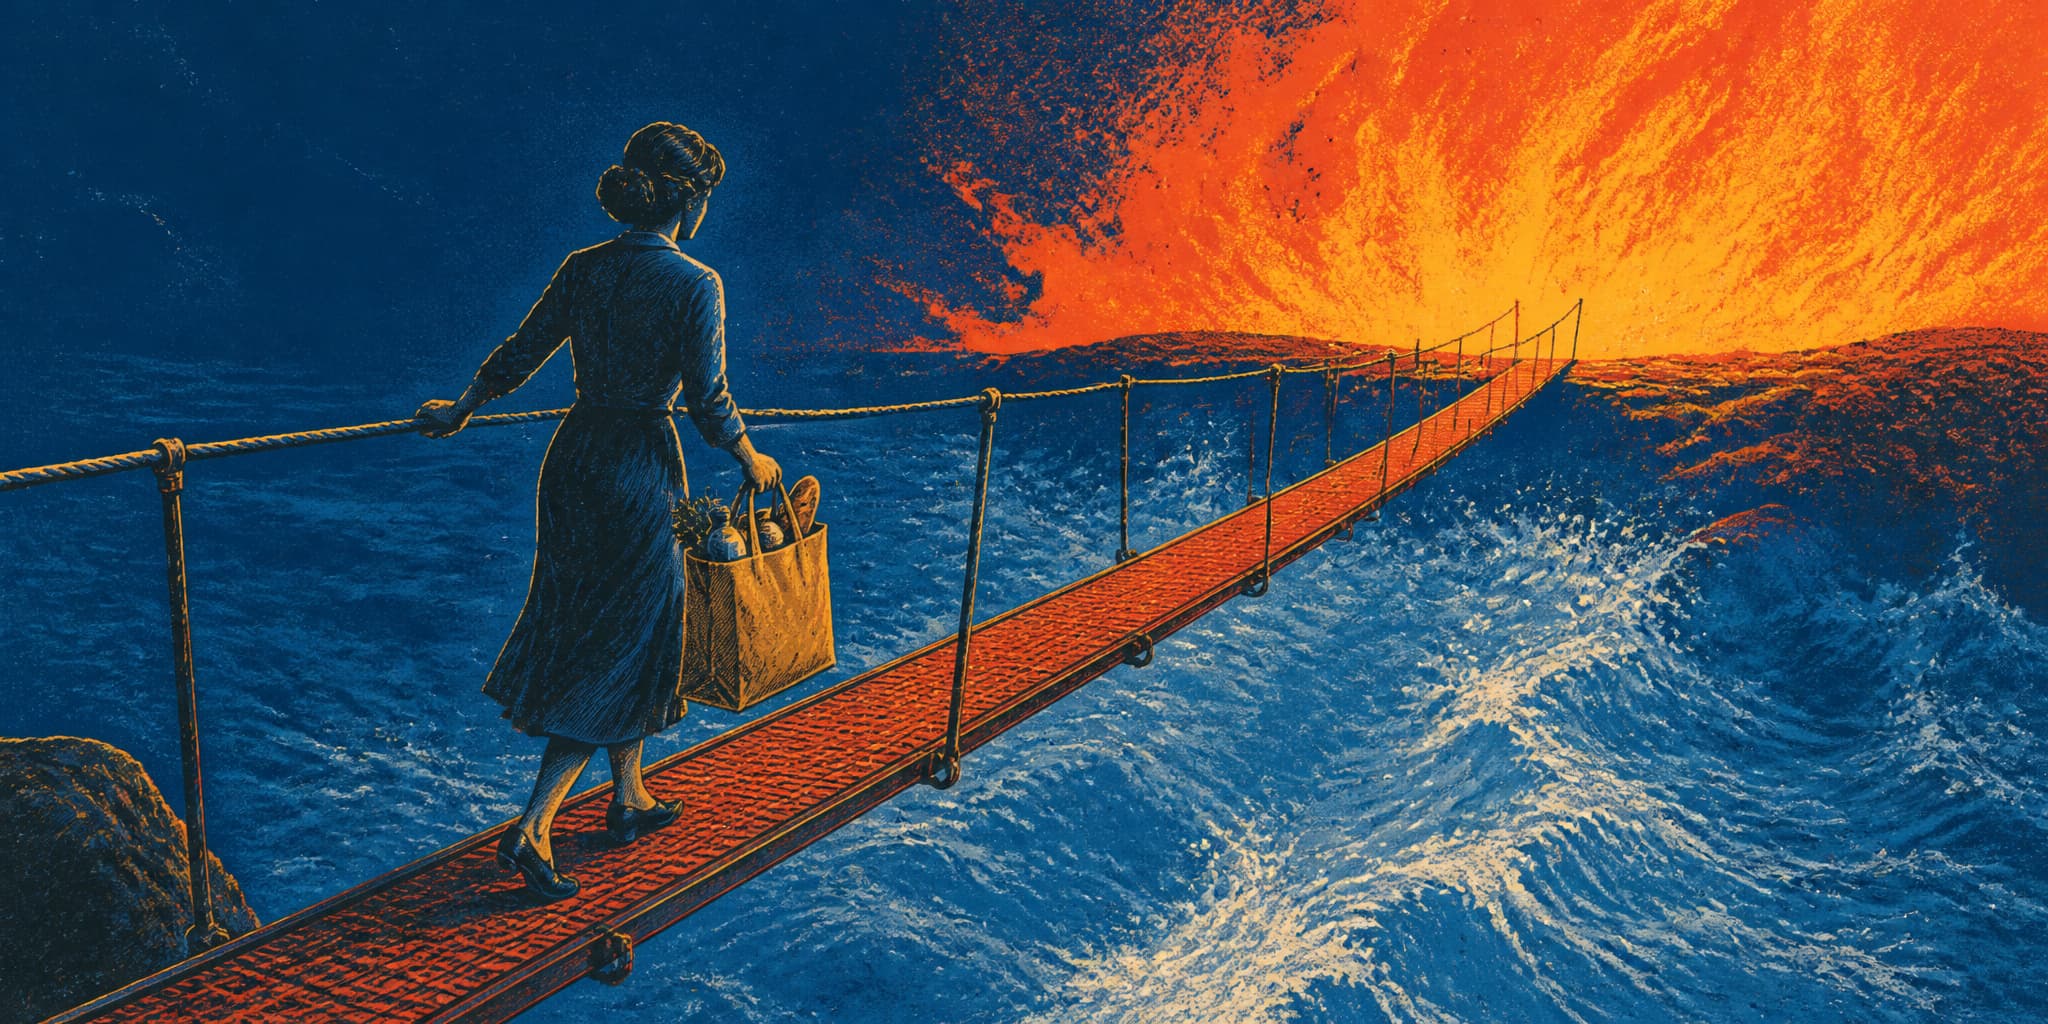
Three weeks later she was crossing the river on a metal walkway about a foot wide that a friend had rigged. The town put a parking space on the far bank so she could reach a vehicle. Every errand, every school run with the two foster children she and her husband were raising, ran across that plank. Out and back. In the rain, in the dark, in November, carrying groceries. A foot of steel over moving water is not a hardship if you're twenty-five and it's dry out. It is a daily negotiation the rest of the time, and nobody logs it anywhere.
O'Bryan put the cost of replacing the bridge — privately owned, as most of these driveway spans are — at roughly $100,000. More than the household could produce without FEMA help. She and her husband had been in Starksboro twenty-four years. "I love our community," she said.
The federal buyout program pays fair market value, either current or pre-disaster depending on the program and the circumstances. It's voluntary, and for plenty of households it's the best thing on offer. But fair market value on a house the river keeps visiting has to go out and buy a different house, at today's mortgage rates, in a market where the replacement costs more than the buyout pays. In Peacham, Vermont, one buyout participant ended up with a new mortgage payment more than three times what she'd been paying on the home she bought in 2020.
That's the arithmetic. Maya Jiménez laid out the timing side of it in "The Clocks" for this publication, following North Carolina households stuck between mortgage payments, temporary housing costs, and buyout timelines that refused to line up.
What fourteen departures cost the town
On September 16, 2026, FEMA approved funding for ninety property buyouts across Vermont. Fourteen of them are in Starksboro.
Town Administrator Amanda Vincent called the approvals a "double-edged sword." Whatever those fourteen parcels had been contributing to the tax base, the remaining owners would now carry.
A funded buyout is not a completed buyout. After the announcement comes appraisal, title work, an offer the owner can take or refuse, closing, demolition, and a permanent deed restriction. As Jiménez reported in "Four Days of Ownership," the public counts of awarded buyouts don't track withdrawals or declined offers. So the town can't budget against the number, because the number hasn't settled.
Vermont's Grand List Stabilization Program reimburses towns for lost buyout-parcel tax revenue at full value for five years, then half for five more. After year ten, the revenue is gone and the land is still open space.
Nobody in the public record has said what Starksboro's budget looks like in year eleven.
The selectboard minutes from June 2025 recorded a highway-fund deficit of roughly $155,000. The town's 2025 hazard plan names voluntary buyouts along Lewis Creek as a priority, on the same roads that took the worst of it. At an August 2025 planning hearing a resident asked what the town could actually do with FEMA-acquired land. Answer: the town owns it, and almost everything is restricted. It can't be sold, built on, or put back on the tax rolls.
The people who remain on those roads sit in those meetings. They hear the deficit read out. Then they drive home past houses that are going to come down and be replaced with deed-restricted grass.
Two maps, two counts
The risk these households are weighing isn't a fixed number. FEMA flood maps mostly show inundation — where water stands during a big flood. Vermont's river-corridor maps show where the channel itself is likely to wander as it eats its banks. A property can sit outside FEMA's high-risk zone and inside the state's erosion corridor, or the other way around, and neither map is wrong. Starksboro's hazard plan carries two different counts of exposed structures — twenty-two in FEMA Zone A, thirty-eight in the state's data — and chalks the gap up to how the maps were digitized.
Huntington's 2022 hazard annex, written before either flood, warns that damage has happened outside the mapped hazard areas and that where the water went last time may not tell you where it goes next. A FEMA-funded scoping study is collecting LiDAR along the Huntington River now and modeling several conditions, with results due at the end of 2026 — after at least one more flood season.
Remaining residents
The average Vermont flood-insurance policy under the federal program runs $1,489 a year. Raising a home's lowest floor can bring the premium down. Whether mitigation has actually produced a different insurance outcome for any particular household in these towns, the public record doesn't say.
And there's a bigger hole in that record. The first-person accounts out of these floodplains come from two kinds of household: the ones who spent money on mitigation and concluded it couldn't hold, like Seoane, and the ones who stay because leaving doesn't pencil, like O'Bryan. The household that hardened the place, believes the site is defensible, and intends to be there in thirty years — the other version of staying — never surfaces in the coverage or the minutes. A project email from late 2024 mentions in passing that a mobile-home owner at the south end of Huntington Acres reportedly turned down a FEMA buyout. No name. No reason. No follow-up.
Maybe that owner made a careful, informed judgment that the property is worth defending. Maybe the refusal had nothing to do with confidence in the river at all. The record doesn't distinguish, and neither does anything downstream of it. The town plows your road. Your parcel stays on the grand list, and your premium reflects the model's opinion of your lot. Not one of those systems has a field for why you stayed.